The Tech Is Here. The Habits Are Still in the Past.
Introduction
“You don’t know what you’re trying to solve,” says Joel Pruis. After more than 25 years in commercial and small-business lending, he's seen how lenders keep fitting new technology to old habits, and lean heavily on information they already know is unreliable. His career across banking, technology, and advising has exposed the distance between completing a loan file and understanding a business.
In this conversation, Joel shares why better data and smarter use of technology could change the way banks approach lending, and why one should question more of the process.
"You’re going to end up writing a check every year for a platform that doesn’t provide any benefit to the organization."

Interview
Sam: Joel, how did a small-business lender end up advising other banks?
Joel: My path into consulting actually started when I was running small-business lending at a community bank in Indianapolis. We had implemented one of the technology solutions, and that company’s sales reps started bringing prospective clients to my office to see how we were using it. After about 18 months of those conversations, I asked if they had a position for me. They did, so I jumped over.
The first site visit I did for a client was with people who had been in my office at the bank about two months before. Suddenly I’m showing up as a representative of the company, and they’re like, “Wait a minute, was that all staged?”
When I got into Cornerstone, the methodologies didn’t change. It was still the same message, the same approach. I was able to expand the array of available technology and platforms I could present to the client and help them pick the optimal one.
Sam: You've worked with more than 200 institutions. When a bank is looking for a new platform, where do you begin?
Joel: I usually start with the basic question: “Why are you looking at purchasing technology? What’s the business case behind it?”
If I hear the off-the-shelf responses, like “We want to reduce redundant data entry, increase capacity, and improve efficiency,” and that's as far as they can go, then I know we have a problem.
I had a client where we got brought in late in the process. They were already evaluating a couple of platforms. We got down to the end, and it was a split decision between the chief lending officer and the chief credit officer. We couldn’t get them to agree.
We boiled it down: What are you truly trying to solve? What business case can you put forward that’s going to pay for this solution and make sure there’s a net benefit to the bank? Neither of them could really define it.
The president asked, “Joel, what would you recommend?” and I answered: “Don’t do anything.” If you don’t know what you’re trying to solve, you’re going to end up writing a check every year for a platform that doesn’t provide any benefit to the organization.
If you don't know what you're trying to fix, there is no technology solution that will meet your needs.
Ultimately, banks need to take ownership of what they're trying to accomplish and challenge vendors to show how their technology meets those needs, rather than letting vendors dictate what those needs should be.
“You don’t know what you’re trying to solve.”
Sam: Do banks ask you to fix things that aren’t actually the problem?
Joel: I often hear, “The platform we're using doesn't work. We need to find a new one.” But too often, it's not the technology but the fact that there's no consistent process or clear understanding of who owns what across the lending lifecycle.
When you bring everyone together to rethink how the process should work, you start uncovering things. An RM might say, “Wait a minute, I do that all the time,” and a Closer responds: “You're doing that, too?” Suddenly, you've found a redundant activity that no one had recognized before.
Once everyone is aligned on the process, you can determine how the technology can best support it.
Sam: Once the process is clear, what should the technology make possible?
Joel: Too often, we see technology for the commercial lending process focusing on creating the credit memo. How do we generate that credit memo? That is too focused on the legacy approach.
It’s got to switch around to focus on the data capture and the process coordination. What data do we need to collect? When is it timely to get that? What’s the quantity of information we need to collect? Who’s going to use it, and how?
Look at the credit memo as just an accumulation of the data that you collected. If we focus on that accumulation of data used to evaluate the risk and define terms and conditions, then we’re really releasing the potential of the process and the technology overall.
“Banks need to take ownership of what they're trying to accomplish… rather than letting vendors dictate what those needs should be.”
Sam: How do you keep lending and credit working from that same picture?
Joel: I think it is a combination of the tools and the process, but I really believe it’s more the overall culture within the organization. It’s really developing teamwork and understanding the roles and responsibilities of each function.
We see that things don’t work well when there’s a lack of discipline in credit analysis and it’s overweighted toward the production side: let’s generate business at whatever cost. Or it’s overweighted toward the credit side, where policy clamps everything down and we cannot get a deal through.
When there’s that good partnership, that healthy tension between production and credit, there’s good output. It’s everybody listening to each other, respecting the other side, and really collaborating to find the path to what can be done for that particular client.
Sam: Does consistency mean treating every business loan the same way?
Joel: If there’s a one-size-fits-all approach to credit and underwriting, you’re probably designing it to work for the most complex and highest-dollar exposure the bank would be taking on. As you apply that down to the smaller exposures, it becomes too onerous a process. It’s about tailoring the level of effort, the level of analysis, to the actual dollars at risk.
I also look at the quality of the information you’re going to collect. As you get into larger businesses, and I’m talking more about commercial and industrial lending, the larger the business, the better the information, particularly the financials.
It still boggles my mind when you get into the small-business side and they’re saying, “We’ve still got to collect the financials.” But how good are those financials? “Oh, they’re junk.” You can’t even reconcile retained earnings from one year to the next. Then why are you relying upon that information in order to make your credit decision?
Sam: Where could AI help lenders find a better credit signal?
Joel: With AI, access to transactional data could be transformational, particularly for small-business lending. Looking at deposit accounts, understanding cash flows, and providing insights can give us a much better picture of risk.
AI can also help uncover correlations between that data and actual loan performance. I often think about Moneyball, the movie, and how they found the numbers that really drove decisions. I'm still waiting for that moment in commercial lending. What's that one number, or set of numbers, in this haystack of data that we're collecting that could change how we evaluate credit?
“Then why are you relying upon that information in order to make your credit decision?”
Sam: What do you wish you’d understood about technology as a banker?
Joel: Challenge the status quo and understand what's possible with technology, rather than trying to make it adapt to legacy ways of doing things.
Don’t just look at an incremental change. Blow everything open and take a look at what’s now possible with the technology you have available.
When we start asking clients, “What would you change? How would you make things better?” they see the small incremental change: “Let’s just modify this a little bit.” Expand it. See the bigger picture.
Sam: So, what will the best underwriters of the next decade do differently?
Joel: It’ll be those who are truly curious about what can be looked at through the lens of an AI tool. They'll also be willing to let go of some of the traditional mechanics. For example, AI might not make all the same adjustments an underwriter would, but how much do those differences really matter? Can we let AI handle it and see if it actually changes the outcome or even gives us new insights? It's about being open to trying new things and seeing what else we can learn.
Sam: Joel, thank you.
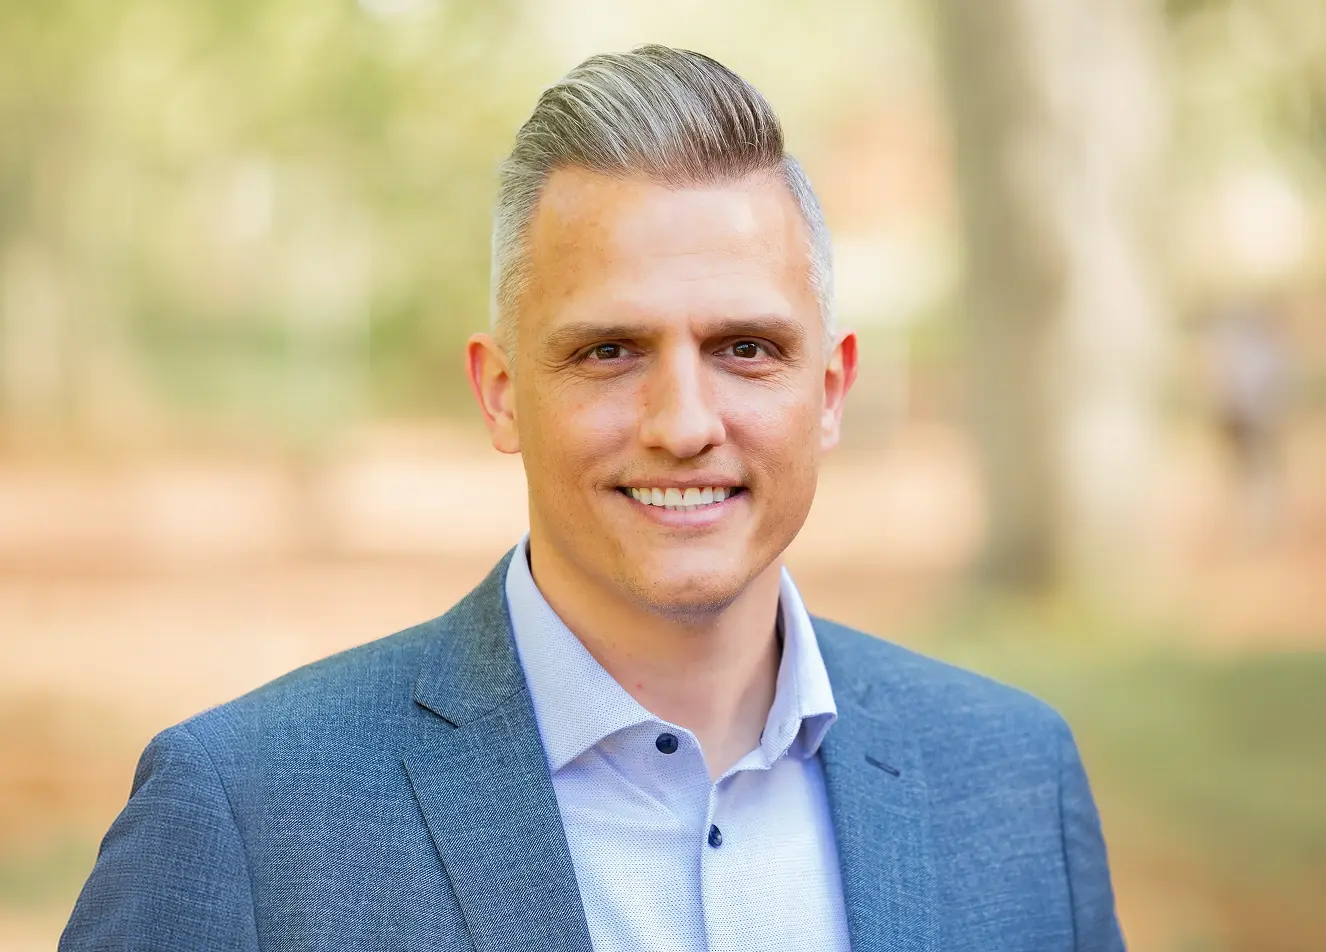
Joel Pruis - Bio
In the commercial and small-business segments, Joel brings more than 25 years of experience delivering fundamental change in the origination and ongoing management of credit relationships. In his role as Senior Director in Cornerstone Advisors’ Lending & Treasury capability, Joel is focused on commercial credit performance improvement, covering policy, process, roles, and responsibilities for both loan origination and ongoing customer management. Joel also facilitates Cornerstone’s Executive Roundtables.










Knowledge is power